How Does Mortgage Work in Monopoly
Understanding how does mortgage work in monopoly is essential for any player who wants to dominate the board. Mortgaging property lets you free up game money when you are low on cash, and unmortgaging later lets you collect full rent again. This guide covers every rule, value, strategy, and mistake to help you master the mortgage system in Monopoly.
The monopoly game has been a family favorite for decades. Players buy properties, build houses, and collect rent from opponents. But what happens when you run low on game money and cannot pay rent? This is where the mortgage system saves the day. Understanding how does mortgage work in monopoly is one of the smartest skills you can learn.
Mortgaging a property means turning it over to the bank in exchange for cash. You stop collecting rent, but you gain breathing room. Later, you can unmortgage the property and start collecting rent again. It is a simple mechanic that adds deep board game strategy to every match. In this article, we will walk through every detail step by step.
Key Takeaways
- Mortgaging property gives you half the deed value back in game money immediately.
- You cannot collect rent on a mortgaged property, so use mortgages strategically.
- Unmortgaging costs the mortgage value plus 10% interest to the bank.
- The mortgage value is printed on each property deed card in Monopoly.
- Holding too many mortgaged properties weakens your cash flow management.
- Mortgages are a powerful board game strategy tool when used at the right time.
- Knowing how does mortgage work in monopoly gives you a serious edge over other players.
📑 Table of Contents
What Is a Mortgage in Monopoly?
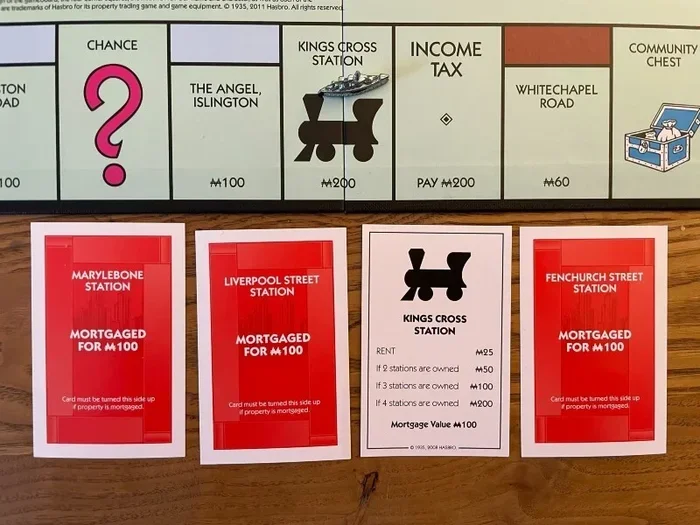
A mortgage in Monopoly is a way to borrow money from the bank using your property as collateral. When you mortgage a property, you flip the deed card face down. The bank pays you the mortgage value listed on the card. You keep that money and can use it however you want. The property is now inactive, meaning no one can collect rent from it.
Think of it like this. You are playing the real estate board game and you just landed on a property owned by your friend. You do not have enough game money to pay rent. If your friend has mortgaged that property, you pay nothing. The mortgage protects the owner from losing money on inactive properties. This is why knowing the mortgage system is so important.
Every property in Monopoly has two values printed on the deed card. The first value is the purchase price. The second value is the mortgage value. The mortgage value is always exactly half of the purchase price. For example, if a property costs 200, the mortgage value is 100. This makes it easy to calculate quickly during gameplay.
Why Do Players Mortgage Properties?
Players mortgage properties for several reasons. The most common reason is to avoid bankruptcy. When you owe more than you can pay, mortgaging gives you instant cash. Another reason is to free up funds for a better opportunity. Maybe you see a color group you want to complete. Mortgaging a less useful property can fund that purchase.
Some players also mortgage properties to confuse their opponents. If your properties are face down, other players do not know which ones are active. This creates uncertainty at the board. It is a clever property trading move that can slow down your opponents’ plans.
How to Mortgage a Property in Monopoly
Mortgaging a property is simple and fast. Follow these steps to do it correctly during your turn.
First, choose the property you want to mortgage. Make sure it does not have any houses or hotels on it. You cannot mortgage a property with buildings on it. If it has houses, you must sell them back to the bank first at half price.
Second, flip the deed card face down. This signals that the property is mortgaged. Place it in front of you so you can keep track of it.
Third, collect the mortgage value from the bank. The banker gives you the cash printed on the deed card. That money is now yours to spend.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value.
Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each property has its own mortgage value. Each
Frequently Asked Questions
What is how does mortgage work in monopoly?
how does mortgage work in monopoly is an important topic with many practical applications.